KHO ruling Koivula: court allows deduction of betting losses in 2020
Decision of 1 Oct 2026 validates €365,606 deduction for bets outside the EEA
Key Takeaways
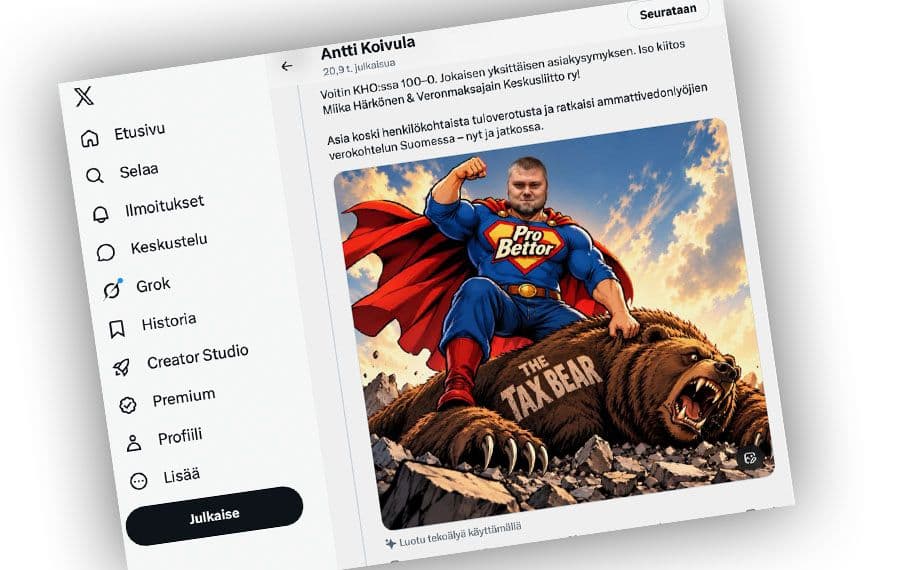
- The KHO ruled on 1 October 2026 in favour of Antti Koivula and allowed a €365,606 deduction for bets placed outside the EEA in 2020.
- In 2020 Koivula recorded 2,145 bets with €365,606 in stakes and €406,713 in returns, yielding a net result of about €41,100.
- Verohallinto had increased Koivula’s taxable base by €112,369.48 and applied a surcharge of €1,154.60, both of which the KHO annulled.
- The court ordered Verohallinto to pay €5,820 in legal costs to Koivula.
By decision of 1 October 2026, the Korkein hallinto-oikeus (KHO) ruled in favour of Antti Koivula and authorised the tax deduction of the 365 606 € he used on bets placed outside the European Economic Area during 2020. The court considered Koivula’s activity in that period to be a "tulonhankkimistoiminta" (income-generating activity) and annulled the previous tax adjustment; the decision also obliges the Finnish Tax Administration, Verohallinto, to reimburse 5 820 € in legal costs.
What the KHO did and why it matters (KHO ruling Koivula)
The KHO ruling focuses on the characterization of Koivula’s betting activity: the court concluded that the volume and planning of his wagers amounted to an activity aimed at generating income. In 2020 Koivula recorded 2 145 bets, with 365 606 € in stakes and 406 713 € in returns, leaving a net positive result of approximately 41 100 €.
The Finnish Tax Administration, Verohallinto, had initially considered deductible only the stakes associated with winning bets and rejected the stakes of lost bets. That interpretation substantially increased Koivula’s taxable base and led to a tax correction whereby, in 2022, Verohallinto increased his employment income by 112 369,48 € and imposed a tax surcharge of 1 154,60 €.
Fiscal context and key figures
Koivula, who is a lawyer specialised in gambling and a former professional bettor, currently serves as compliance director at Hippos ATG Oy. In his public testimony he said he had already paid about 12 000 € on the actual net profit of ≈41 100 € and faced an additional claim that was initially about ≈57 000 €, an amount he estimated had grown to ≈75 000 € with interest and surcharges. The case had a significant personal and financial impact: Koivula said he lacked liquidity to meet extraordinary payments and that his family relied on his income.
In addition to annulling the tax correction and its surcharge, the KHO returned the obligation to Verohallinto to reimburse legal costs of 5 820 €.
Scope of the ruling: which costs remain in dispute
The court explicitly ruled that Koivula was entitled to deduct bets placed outside the EEA in 2020 totalling 365 606 €. Not all items Koivula claimed as deductible were resolved in his favour in this decision. The allowance of certain deductions was remitted to the tax rectification board (oikaisulautakunta). Among the outstanding items are:
telephone and internet connection costs related to the activity;
workspace costs and office supplies;
office and publication expenses;
business travel;
tickets to football matches.
The KHO did not set precise quantitative parameters — it did not establish, for example, a threshold of hours devoted to the activity nor a minimum stake amount. The court explained that the assessment must be based on the totality of conduct: systematic nature, persistence and the purpose of obtaining income.
Professional profile of Koivula and how it influenced the decision
Antti Koivula stated in interviews that between 2010 and 2020 his family and he supported themselves through planned betting activity. At the most intense periods he said he devoted between 50–100 hours per week to the activity; in less intense phases, 30–50 hours per week. His focus was on Finnish football matches and detecting odds discrepancies through analysis and information capture.
Although the KHO did not treat the activity as a trade or business (the term "elinkeinotoiminta" was not applied), the court did consider that Koivula’s conduct was sustained and organised and therefore fit the statutory concept of income-generating activity under the income tax law.
"The ruling may give others who operated professionally in the past a basis to review old tax assessments," Koivula said in one of his public statements, according to local media.
Reactions and possible regulatory consequences
Koivula described the ruling as relevant for other professional bettors in Finland. He also suggested that, in view of a possible future national licensing system, the decision could affect how people who have bet professionally are treated for tax purposes. In his comments he expressed interest in improved consumer protection within gambling regulation and criticised customer service practices on extraterritorial platforms.
For operators, suppliers and tax advisers the ruling sets a precedent that will force clearer documentation criteria and a review of how activities of revenue-generating players are classified. It is likely tax advisers will re-examine past files of clients who bet professionally and consider filing appeals or rectification requests.
What operators and advisers should consider (deduction of bets)
Documentation: keep clear records of stakes, returns, hours and work methodology.
Market distinction: the ruling applied to bets organised outside the EEA in 2020; market jurisdiction is relevant.
Case-by-case assessment: the KHO insists on a valuation of the totality of activity, not fixed thresholds.
The judgment also has practical compliance implications for in-house tax and compliance departments at operators and bookmakers, which will need to consider how to respond to historical claims and what evidence is accepted to justify the professional nature of the activity.
Materials and references
The KHO decision is available in the court’s decision database; Finnish media that covered the news include Taloustaito, Nettipokeri.com and Atleetti. For regulatory matters and the impact on public policy, sector stakeholders can follow the discussion in the section of [regulation](/regulation) and in professional analysis in [b2b](/b2b).
Frequently Asked Questions
What exactly did the KHO decide in Antti Koivula’s case?
On 1 October 2026 the KHO ruled that Koivula’s activity in 2020 constituted income-generating activity and authorised the deduction of €365,606 in bets placed outside the EEA; it annulled the previous tax correction and ordered Verohallinto to pay €5,820 in legal costs.
What betting and tax figures are central to the Koivula decision?
In 2020 Koivula placed 2,145 bets with total stakes of €365,606 and returns of €406,713, leaving a net result of roughly €41,100; Verohallinto had increased his taxable base by €112,369.48 in 2022.
Did the judgement set objective thresholds like hours or stake minima to define professional activity?
No, the KHO did not establish numeric thresholds such as hours or minimum stakes; it said the assessment must consider the totality of conduct — systematic nature, persistence and the purpose of obtaining income — to determine deductibility.
Which expense items claimed by Koivula remain unresolved by the judgment?
Pending before the tax rectification board are the deductibility of phone and internet costs, workspace and office supplies, publications, business travel and football match tickets.
Tags
About the author

Emilio Navarro
Industry Technology Correspondent
Emilio Navarro covers the cross-cutting technology and business of iGaming — platforms, data and AI, compliance tooling, affiliate marketing, financial results, and the stories that fit no single rubric. The reports open with the announcement, cite vendors and figures exactly as published, and keep a healthy distance from press-release language. When a supplier unveils a new engine or the advertising rulebook changes, Emilio Navarro reports what genuinely changes.
More from Emilio Navarro









