SJM Holdings first half 2026: revenue falls 21% while margin rises
Without nine satellite casinos, total revenue was HK$11.59bn; adjusted EBITDA up 3.3%.
Key Takeaways
- SJM Holdings reported total net revenue of HK$11.59 billion in H1 2026, a 20.8% decline versus 2025.
- Adjusted EBITDA rose 3.3% to HK$1.70 billion and the operating margin expanded to 14.7% from 11.2%.
- SJM lost nine satellite casinos that contributed HK$5,647 million of GGR in H1 2025, and group market share in Macau fell to 9.8%.
- Group debt rose to HK$30.22 billion and gearing increased to 56.2%; 63.7% of borrowings mature in one to two years.
- Grand Lisboa Palace increased GGR 12.9% to HK$3,315 million but saw adjusted property EBITDA fall to HK$22 million.
SJM Holdings published on 28 September its interim report covering the first half ended 30 June 2026; the group recorded total net revenue of HK$11.59 billion (approx. $1.49bn), a 20.8% decline from HK$14.64 billion, while adjusted EBITDA rose 3.3% to HK$1.70 billion and the operating margin improved to 14.7% from 11.2%. Loss attributable to shareholders widened to HK$295 million from HK$182 million and net debt increased to HK$30.22 billion, according to the same report.
First half numbers look different once satellite casinos are excluded
The key difference in these figures is that these are SJM's first accounts since the nine satellite casinos left its books. As at 30 June 2025 SJM operated nine satellite casinos; during H1 2026 it did not. The report notes that "On 30 December 2025, Casino L'Arc Macau became one of the self-promoted casinos under SJM, while the other eight satellite casinos ceased operations during 2025." Macau's 2022 gaming law amendment allowed satellite casinos to operate from concessionaire-owned premises only until the end of 2025, and that effect shows in the revenue line.
Total net revenue fell 20.8% to HK$11,590 million and net gaming revenue declined 22.5% to HK$10,560 million. Gross gaming revenue (GGR) was HK$12,084 million (approx. $1.55bn), an 18.5% drop. By breakdown, non-rolling GGR, which covers mass table play, fell 21.8% and electronic gaming dropped 29.1%, while rolling GGR rose 32.9% to HK$1,461 million. Commissions and incentives increased 27.8% to HK$1,524 million, a market-wide trend the report highlights.
Market and share: SJM loses share in Macau
SJM reported a market share of 9.8% of Macau GGR in the period, down from 12.9% a year earlier. Peninsula mass table share was 12.3% (16.1% a year earlier) and VIP share 4.2% (3.7% a year earlier). The fall in share reflects the exit of the nine satellite casinos, which in H1 2025 contributed HK$5,647 million of GGR.
More market context is available in our coverage on [news](/news) about Macau.
More gaming revenue from owned assets: margin improves because satellites were low-margin
Although the topline fell, operating profitability improved because the revenue contributed by the satellite casinos had very low margins. In H1 2025 the nine satellites generated HK$5,647 million of GGR but only HK$153 million of adjusted property EBITDA, a margin below 3%. Excluding them, the group's adjusted EBITDA rose 3.3% to HK$1,701 million (approx. $218m) and the margin expanded to 14.7%.
Excluding the satellites, SJM's own properties lifted GGR to HK$12,084 million from HK$9,174 million a year earlier, an approximate 32% increase according to the report's reconciliations. Gains came mainly from Peninsula casinos: the rest of properties, which includes Casino Lisboa, Casino Oceanus at Jai Alai and Casino L'Arc (acquired in December 2025), saw GGR rise 85.7% to HK$4,931 million and adjusted property EBITDA increase 44.2% to HK$939 million.
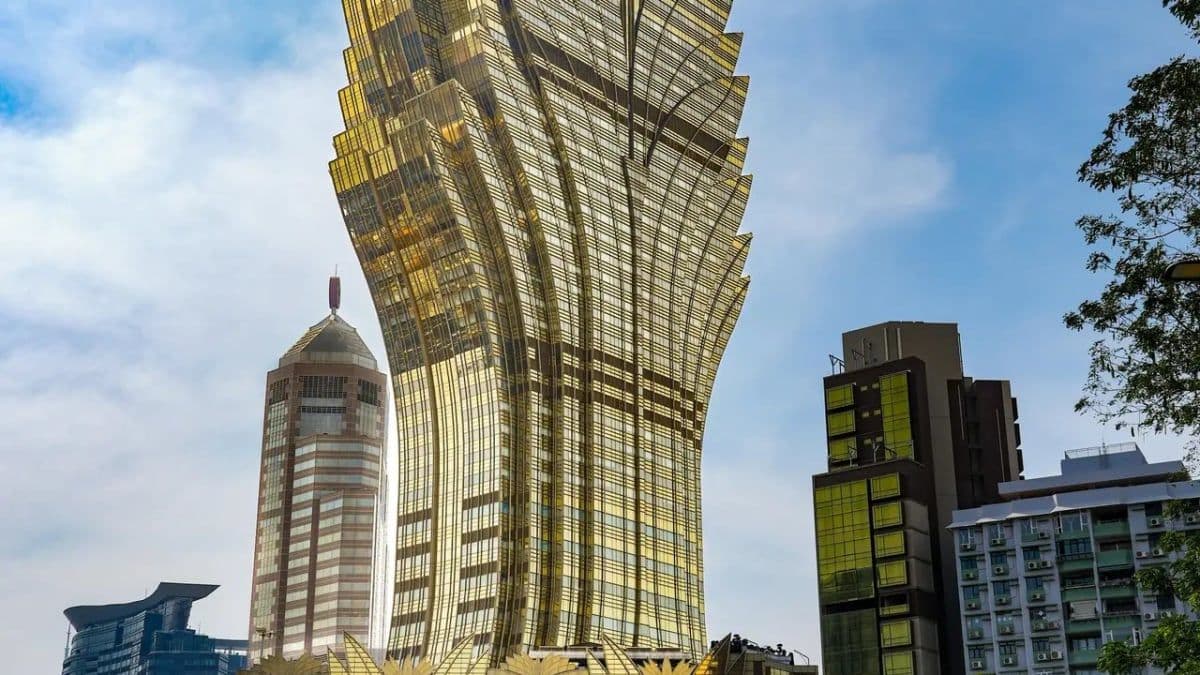
Grand Lisboa increased its GGR 7.1% to HK$3,838 million, with property EBITDA stable at HK$860 million. Grand Lisboa Palace in Cotai improved GGR 12.9% to HK$3,315 million, but its adjusted property EBITDA plunged 73.2% to HK$22 million and hotel occupancy fell to 92.9% from 98.1%.
"Following the successful completion of the transition to a direct management model, management's focus has shifted towards optimising asset productivity, strengthening the premium customer proposition and further enhancing the Group's overall competitiveness and operational resilience," management stated in the report.
Balance sheet, debt and maturities: leverage shapes the agenda
As at 30 June SJM held HK$3,486 million in cash, bank balances and deposits, against HK$30,217 million (approx. $3.87bn) of debt, compared with HK$3,335 million and HK$27,257 million at the prior year-end. Bank borrowings rose to HK$18,347 million from HK$16,222 million at end-2025.
In January a subsidiary issued US$540 million of senior notes at 6.50% due 2031 to refinance syndicated loans; notes maturing in 2026 were no longer outstanding at 30 June. Of the HK$11.5 billion revolver, HK$2.35 billion was available at 30 June. Gearing rose to 56.2% from 54.4% and 63.7% of borrowings will mature in one to two years; 15.6% matures in less than a year. There is also a convertible bond of HK$1,906 million held by the controlling shareholder, STDM, maturing on 22 June 2027.
The company has launched a cost-management and operational optimisation programme and has moved tables from satellites to owned properties, including phase two of the Crystal Palace area at Hotel Lisboa, opened on 10 August, and new gaming areas at Grand Lisboa Palace. Headcount reduced to approximately 19,400 employees at 30 June from ~20,300 a year earlier.
Grand Lisboa Palace remains the critical test for the transition
The table reallocation aimed to make the Cotai resort profitable. GGR rose, but HK$22 million of property EBITDA on almost HK$3.94 billion of revenue suggests the extra volume comes with high commissions and incentives. SJM says it is reconfiguring floors for premium mass and rolling play; until that improves property EBITDA, Peninsula properties will continue to underpin group results.
The closure of the satellite casinos has left SJM a smaller revenue company but with a higher operating margin on a significant debt base. H2 2026 will show whether the productivity programme can convert that margin improvement into enough profit growth to meet upcoming maturities.
For operators, suppliers and analysts in the B2B space the priority will be SJM's ability to lift Grand Lisboa Palace performance without eroding group cash flow; operational and cost details will set the refinancing timetable.
Frequently Asked Questions
Why did SJM's revenue fall in the first half of 2026?
Revenue fell because SJM no longer had the nine satellite casinos that in H1 2025 contributed HK$5,647 million of GGR; as a result total net revenue declined 20.8% to HK$11.59 billion.
How did the operating margin improve despite the revenue decline?
The operating margin improved because the satellite casinos had very low margins; excluding them the group's adjusted EBITDA rose 3.3% to HK$1,701 million and the margin widened to 14.7%.
What is SJM's debt position and what are the key maturities?
Debt increased to HK$30.22 billion as at 30 June and gearing rose to 56.2%; 63.7% of borrowings mature in one to two years, 15.6% in less than a year, and there is a HK$1,906 million convertible bond held by the controlling shareholder maturing 22 June 2027.
What operational issue persists at Grand Lisboa Palace?
Grand Lisboa Palace grew GGR to HK$3,315 million but its adjusted property EBITDA fell to HK$22 million, indicating that additional volume is being accompanied by high commissions and incentives that reduce profitability.
Tags
About the author

Emilio Navarro
Industry Technology Correspondent
Emilio Navarro covers the cross-cutting technology and business of iGaming — platforms, data and AI, compliance tooling, affiliate marketing, financial results, and the stories that fit no single rubric. The reports open with the announcement, cite vendors and figures exactly as published, and keep a healthy distance from press-release language. When a supplier unveils a new engine or the advertising rulebook changes, Emilio Navarro reports what genuinely changes.
More from Emilio Navarro









