BetMGM posts 7% revenue rise and 112% jump in adjusted EBITDA in Q3 2026
Online casino and sportsbook sales grew while active users fell slightly to 878,000.
Key Takeaways
- BetMGM reported Q3 revenue of $710 million for the quarter ended 30 September 2026, up 7% year on year.
- Adjusted EBITDA rose 112% to $86 million in Q3 2026.
- Online casino revenue was $483 million (+6%) and sportsbook revenue $216 million (+7%).
- Average monthly users declined 3% to 878,000 while net gaming income per user rose 4% (casino) and 18% (betting).
- Total sports betting volume grew 3% to $3.24 billion and bets per user increased 13%.
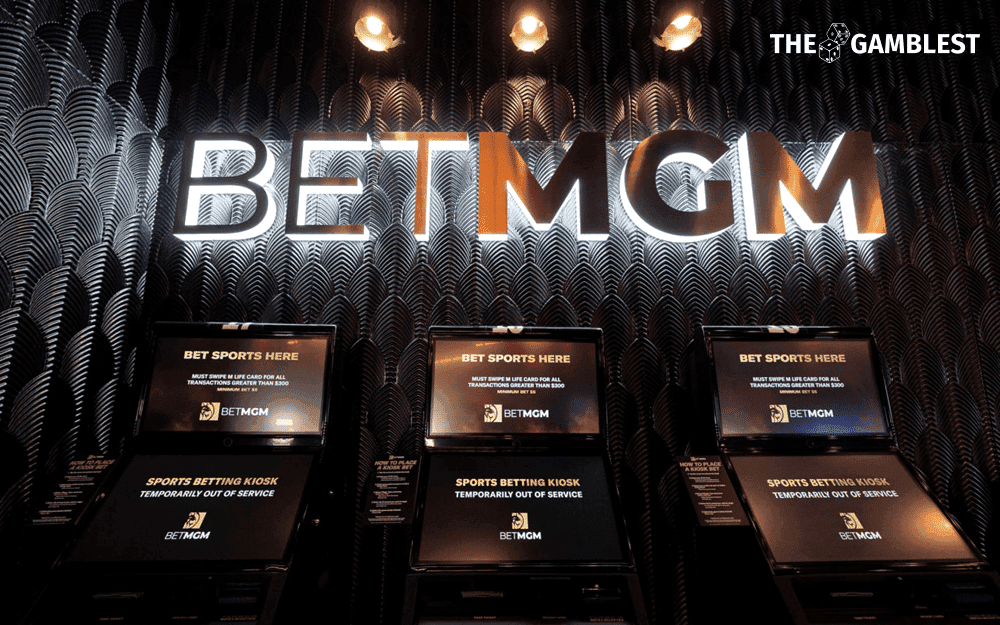
BetMGM reported revenue of $710 million for the quarter ended 30 September 2026, a 7% year-on-year increase, and adjusted EBITDA of $86 million, up 112% versus the same period last year. The results arrived alongside a 3% decline in average monthly active users to 878,000 even as net gaming income and bets per user rose across product lines.
BetMGM Q3 results: top-line and profitability
Revenue for the third quarter was $710 million, a 7% increase year on year. Adjusted EBITDA climbed to $86 million, a 112% increase compared with Q3 in the prior year. Management said these gains were driven by stronger per-user economics rather than growth in active accounts.
"BetMGM delivered a strong Q3 as we continue to execute with discipline and generate profitable growth," said Adam Greenblatt, chief executive officer of BetMGM.
The company highlighted product stability and performance upgrades in its statement, noting improvements in speed, stability and responsiveness ahead of the football season as contributors to the quarter's results.
Online casino revenue and player economics
Revenue from online casino games increased by 6% to $483 million. While the total number of average monthly users fell 3% to 878,000, the online casino segment saw a 4% rise in net gaming income per user and higher engagement measured by bets per user.
Operators and suppliers will note the distinction between user counts and per-user economics: the company reported improvements in yield even as the active base contracted. The statement emphasised prioritisation of the iGaming franchise as a core strength for the business.
Sportsbook revenue, volumes and per-user gains
Sportsbook revenue rose 7% to $216 million. Total sports betting volume increased by 3% to $3.24 billion for the quarter. Net gaming income per user in the betting segment increased by 18%, and the number of bets placed per user improved by 13%.
These figures point to higher monetisation per bettor rather than broadening the active customer base. The sportsbook performance coincided with the company flagging operational nimbleness in a highly competitive market as a factor in the results.
Customer metrics and what moved the needle
The company reported three concrete customer metrics that tell a consistent story: average monthly users at 878,000 (-3%), higher net gaming income per user (+4% casino; +18% betting) and bets per user up 13%. Together they show revenue growth driven by deeper engagement with existing customers rather than expansion of the player pool.
Adam Greenblatt linked the results to both product improvements and cost discipline.
"Our product is stronger than it's ever been, with significant improvements to speed, stability, and responsiveness ahead of this football season," Greenblatt said.
He also said management remains on track to deliver against the company's 2026 guidance, pointing to positive cash flow and adjusted EBITDA as supporting the long-term outlook.
What operators and vendors should read from the numbers
For platform suppliers and third-party vendors, the quarter highlights demand for investments that raise per-user value: performance engineering, retention-facing product features and in-play betting capabilities. The emphasis on stability and responsiveness before the football season suggests continued priority on latency and uptime work.
Product teams focused on iGaming will see the $483 million casino revenue line as confirmation that monetisation improvements can offset modest user-base contraction. Sportsbook vendors should register the 18% rise in net gaming income per user and the 13% increase in bets-per-user as indicators of higher yield requirements from operators.
Guidance and outlook
BetMGM reiterated confidence in its 2026 guidance by citing the quarter's positive cash flow and the jump in adjusted EBITDA. Management described the operating posture as prioritising areas of strength, particularly iGaming, while remaining "operationally nimble as we navigate a highly competitive environment."
For market observers, the key items to watch after this report are whether BetMGM can stabilise or grow its active user base while maintaining the improved per-user economics and whether product improvements translate into retention gains over the football season.
Frequently Asked Questions
What were BetMGM's headline financials for Q3 2026?
BetMGM reported revenue of $710 million for the quarter ended 30 September 2026 and adjusted EBITDA of $86 million. Revenue was up 7% year on year and adjusted EBITDA increased 112% versus the prior-year quarter.
How did BetMGM's online casino and sportsbook perform in Q3?
Online casino revenue rose 6% to $483 million and sportsbook revenue increased 7% to $216 million. The company also reported a 4% rise in net gaming income per user for casino and an 18% rise for betting.
Did BetMGM grow its active player base in Q3?
No, average monthly active users declined 3% to 878,000 in Q3 2026. The company offset the decline by improving per-user monetisation, including a 13% increase in bets per user.
What volume did BetMGM report for sports betting in Q3?
BetMGM reported total sports betting volume of $3.24 billion for the quarter, a 3% increase year on year.
Tags
About the author
Oliver Grant
Industry Technology Correspondent
Oliver Grant covers the technology and business machinery of iGaming — platform and data deals, AI and compliance tooling, affiliate and marketing shifts, and the quarterly numbers behind them. The reports lead with the announcement, name the vendors and figures exactly as published, and separate genuine capability from press-release promise. When a supplier ships a new engine or a regulator tightens ad rules, Oliver Grant explains what actually changes for the companies involved.
More from Oliver Grant