SkyCity Agrees NZ$221m Sale of The Grand Hotel to Reduce Debt
Deal to raise NZ$295.5m in asset sales, settlement targeted mid‑December 2026 pending OIO consent.
Key Takeaways
- SkyCity signed a binding agreement on 16 October 2026 to sell The Grand Hotel for NZ$221 million to Eden Global Capital Private Limited and Auckland City Collective Limited.
- The deal is conditional on Overseas Investment Office consent and targets settlement in mid‑December 2026 with SkyCity managing the hotel until 30 June 2027.
- Proceeds raise SkyCity's asset monetisation total to NZ$295.5 million versus an original target of about NZ$200 million.
- SkyCity ended FY26 with net debt of NZ$591 million and 3.1x covenant leverage; the sale is intended to reduce leverage below 2.0x EBITDA in FY27, excluding a NZ$30 million online licence payment.
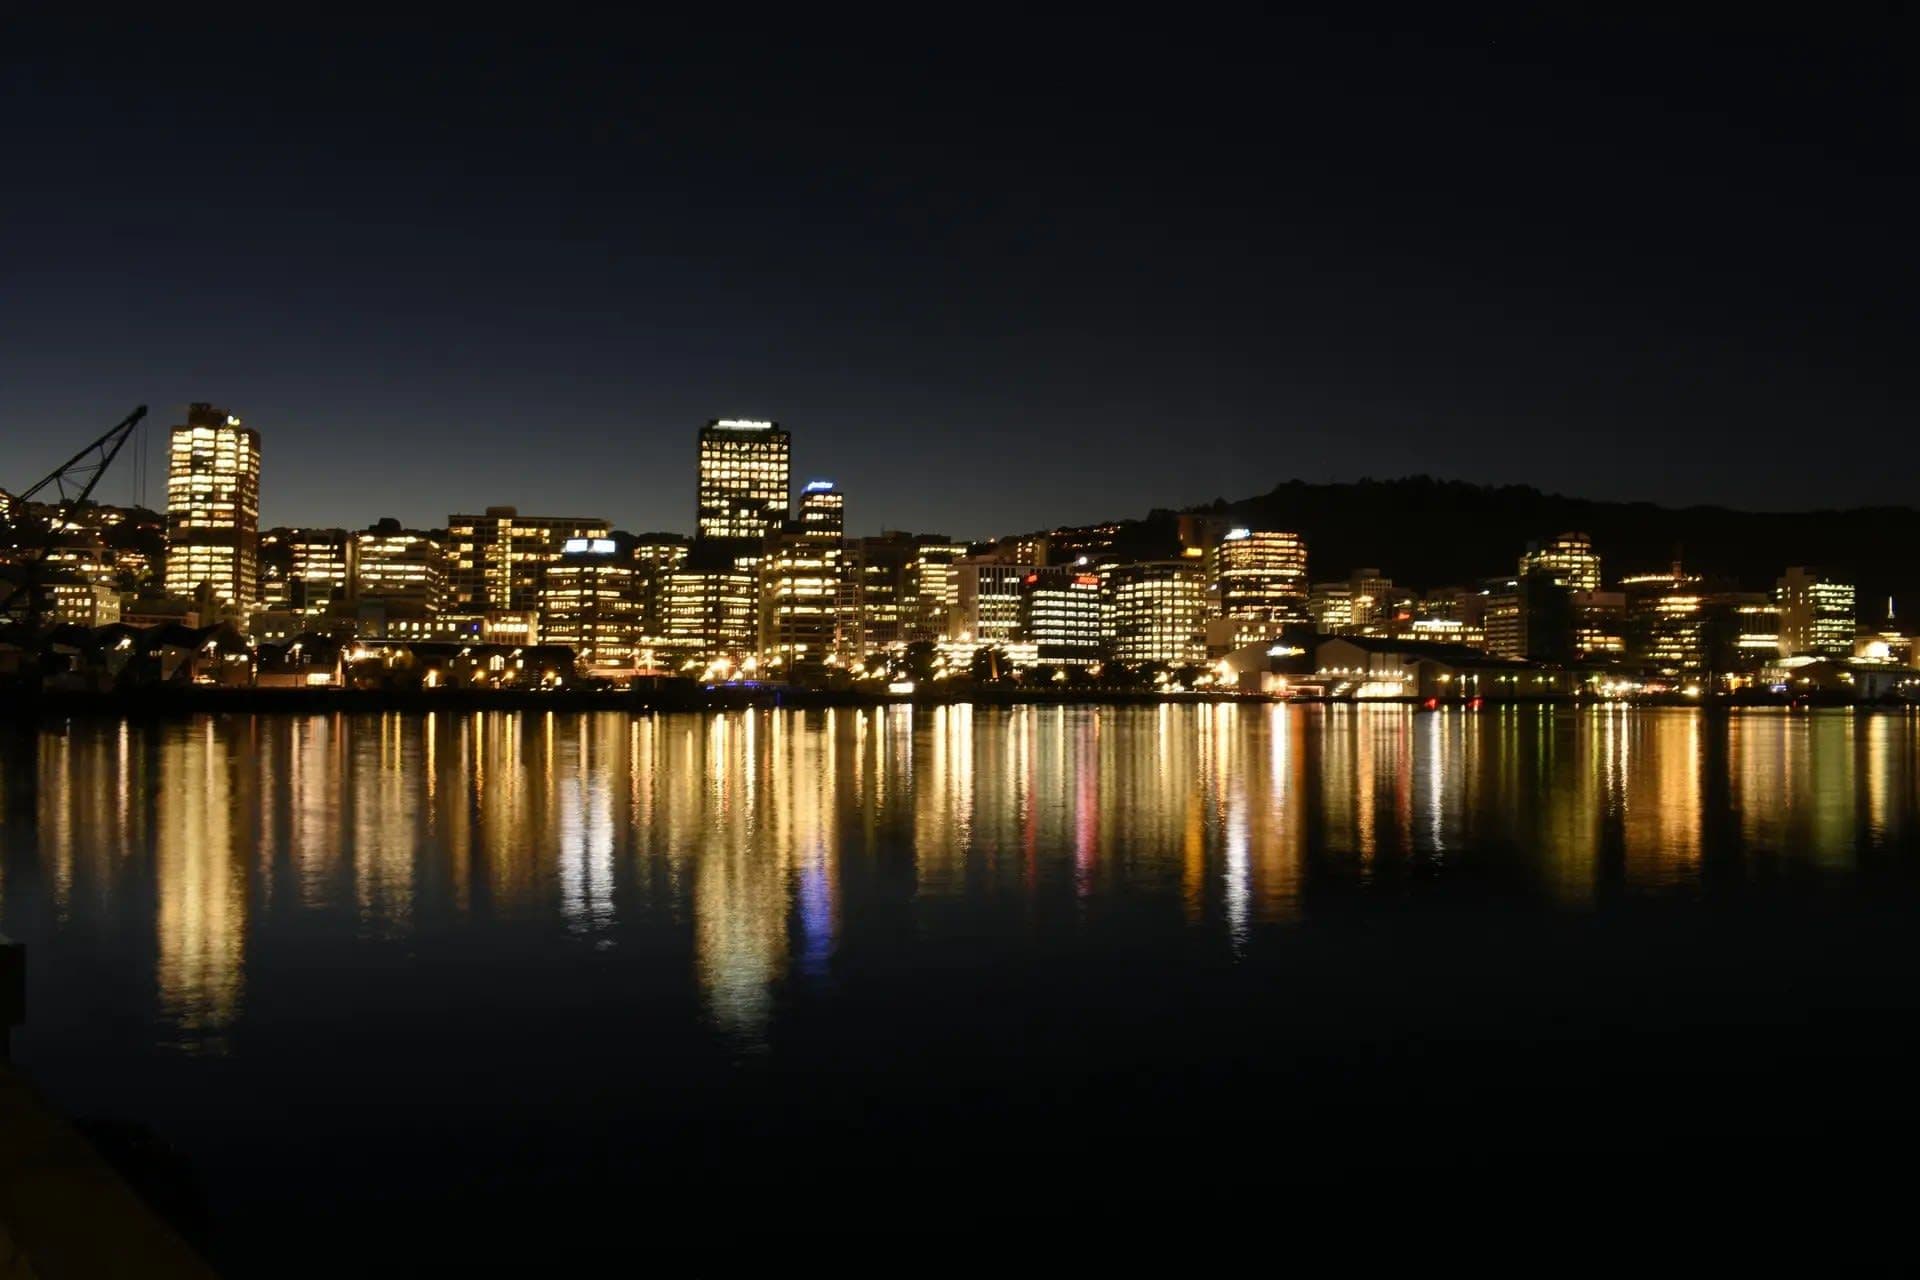
SkyCity Entertainment Group signed a binding sale and purchase agreement on 16 October 2026 to sell The Grand Hotel in Auckland for NZ$221 million (approximately $124 million) to Eden Global Capital Private Limited and Auckland City Collective Limited. The agreement is conditional on consent from New Zealand's Overseas Investment Office, and SkyCity is targeting settlement in mid‑December 2026 while continuing to manage the hotel until 30 June 2027.
SkyCity Grand Hotel sale and the buyers
SkyCity Entertainment Group, the casino operator listed on the NZX and ASX, disclosed the binding agreement in a market release to the NZX and ASX on 16 October 2026. The sale price is NZ$221 million and the purchasers are Eden Global Capital Private Limited and Auckland City Collective Limited. SkyCity's release describes those buyers as constituents of a privately owned property investment and development organisation with interests in Australia, Singapore and Southeast Asia; the parent group is not named.
The agreement includes a condition requiring approval from the New Zealand Overseas Investment Office. SkyCity said it expects the outstanding conditions to be satisfied through the remainder of 2026 and is targeting mid‑December 2026 for settlement. As part of the transition the company will continue to manage and operate The Grand for the buyer until 30 June 2027; SkyCity did not disclose the commercial terms of that management arrangement.
"With the sale we will have raised proceeds above our commitment to shareholders, materially strengthened our balance sheet and enhanced our financial flexibility," said chief executive Jason Walbridge.
Scott Collins, a director of the two buying companies, said the group had previously owned commercial assets in Auckland and was pleased to "redeploy capital back into New Zealand."
How the transaction fits SkyCity's asset monetisation programme
The Grand sale follows the earlier, settled disposal of SkyCity's Auckland office and investment properties for NZ$74.5 million. Taken together, those two transactions bring the asset monetisation programme to NZ$295.5 million, against an original target of about NZ$200 million and an August guidance range of NZ$275 million to NZ$300 million.
SkyCity has said the proceeds from The Grand will be used to repay debt. The company signalled that the sale will take its leverage below 2.0 times EBITDA in FY27 on a covenant basis; that leverage path was set before the company disclosed the payment required to apply for online casino licences.
Balance sheet metrics, online licence cost and timing risks
SkyCity ended FY26 with net debt of NZ$591 million (approximately $332 million) and covenant leverage of 3.1 times EBITDA, according to its full‑year results published on 20 August 2026. In August 2025 the company completed a NZ$240 million equity raise alongside the asset sales programme.
On 13 October 2026 SkyCity confirmed it had won the right to apply for two New Zealand online casino licences at NZ$15 million each excluding GST, totalling NZ$30 million (approximately $16.8 million). SkyCity's stated leverage target below 2.0 times excludes this NZ$30 million licence payment.
Timing matters: if Overseas Investment Office consent or other conditions delay settlement past mid‑December, the intended debt reduction will not occur on schedule and SkyCity's ability to fund the online licences from a repaired balance sheet will be affected.
Strategic context: Adelaide process, takeover approaches and market reaction
SkyCity is also running a formal sale of SkyCity Adelaide and has engaged advisers to consider offers for the whole group. Earlier non‑binding takeover proposals at NZ$0.70 and NZ$0.75 a share were rejected; SkyCity's shares were trading at NZ$0.68 late on Friday, up about 3% on Thursday's close according to Yahoo Finance.
The company has argued that asset sales make the group easier to value. By monetising the Auckland office and The Grand, and running a sale process for Adelaide, the board said it strengthens its negotiating position after earlier approaches that the board considered undervalued the business.
SkyCity has said it will update shareholders at its annual meeting on 21 October 2026.
Operational and regulatory caveats
The company did not disclose The Grand's book value, whether it expects to record a gain or loss on sale, nor the hotel's standalone EBITDA, so the NZ$221 million price cannot be read as a multiple from the information provided. The Grand was not classified as held for sale at 30 June 2026, because no binding offer had been received at that reporting date, and the group's annual report therefore does not show a separate carrying value for the hotel.
The sale reduces SkyCity's operational control of the hotel precinct after the management transition ends on 30 June 2027; from that point the hotel–precinct relationship will be contractual rather than ownership‑based, and the market link between hotel accommodation and gaming revenue will be maintained only if the parties agree.
Regulatory and legal history elsewhere in the group remains relevant. SkyCity Adelaide was ordered in 2024 to pay an A$67 million civil penalty in proceedings brought by AUSTRAC, Australia's financial intelligence agency. S&P Global, which rates SkyCity at BBB‑ with a negative outlook, has said it would review that outlook on settlement of The Grand sale.
What operators, investors and advisers should watch next
Key near‑term items are Overseas Investment Office consent, completion of settlement targeted for mid‑December 2026, and the 21 October annual meeting update. The interaction between asset‑sale proceeds and the NZ$30 million online licence outlay will determine how quickly SkyCity can pursue its online strategy from a reduced leverage base.
Observers should also watch the SkyCity Adelaide sale process for indications of valuation multiples bidders apply to a simpler, de‑levered group.
Frequently Asked Questions
Who is buying The Grand Hotel and for how much?
Eden Global Capital Private Limited and Auckland City Collective Limited are buying The Grand Hotel for NZ$221 million (approximately $124 million). The buyers are described as constituents of a privately owned property investment and development group with interests in Australia, Singapore and Southeast Asia.
When will the sale settle and what conditions remain?
SkyCity is targeting settlement in mid‑December 2026, subject to consent from the New Zealand Overseas Investment Office and other transactional conditions. SkyCity expects those conditions to be satisfied through the rest of 2026.
How will SkyCity use the proceeds from the sale?
SkyCity will apply the proceeds to repay debt as part of its asset monetisation programme, which now totals NZ$295.5 million after the office and hotel sales, exceeding the original NZ$200 million target.
How does the sale affect SkyCity's leverage and online licence plans?
The company expects the Grand sale to reduce covenant leverage below 2.0 times EBITDA in FY27; that leverage path excludes the NZ$30 million cost of two online casino licence applications (NZ$15 million each). Timing of settlement will therefore affect how quickly SkyCity can fund the online licences from a repaired balance sheet.
Tags
About the author
Marcus Webb
Industry Deals Correspondent
Marcus Webb covers the deal flow of the gambling industry — operator strategy, M&A, market entries, and product launches from sportsbook rebrands to full platform migrations. The reports name the companies, valuations, and jurisdictions exactly as disclosed and separate the announcement from its market impact. When a group consolidates a brand or a challenger launches into a new state, Marcus Webb explains who gains, who pays, and what closes next quarter.
More from Marcus Webb