CFTC proposes to classify event contracts as swaps while excluding casino gambling
Agency issues proposed swap definition and an interim final rule that preserves state-regulated gambling.
Key Takeaways
- On 9 October 2026 the CFTC proposed to add "event contracts" to the swap definition and adopted an interim final rule excluding qualifying casino‑style gambling.
- The interim final exclusion takes effect on Federal Register publication and will be followed by a 30‑day public comment period.
- The proposed swap inclusion must be finalised before taking effect and responds to conflicting rulings from the Third, Ninth and Sixth Circuits.
- To qualify for the gambling exclusion a product must be state or tribe‑authorised and not traded on an organised exchange.
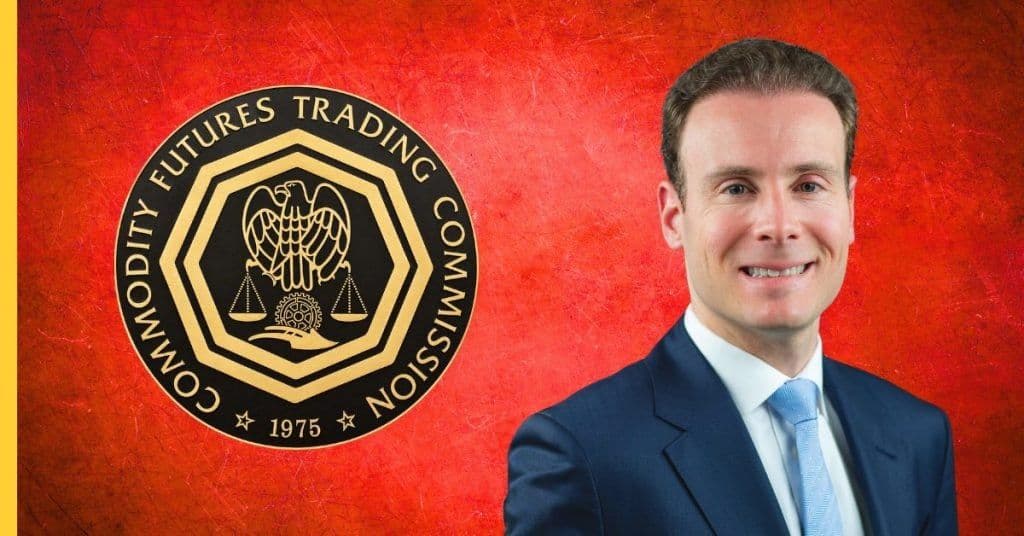
The Commodity Futures Trading Commission proposed on 9 October 2026 to amend the definition of “swap” to explicitly cover event contracts based on sports, politics, culture and weather, and concurrently adopted an interim final rule excluding qualifying casino-style gambling and sportsbook wagers from that definition. The proposed amendment would require a final rule before taking effect; the interim final exclusion takes effect on publication in the Federal Register and will be followed by a 30‑day public comment period.
What the CFTC proposed for sports and event contracts
The CFTC’s rulemaking package would add a discrete category to the statutory swap definition in the Commodity Exchange Act to cover "event contracts, including those based on sports-, politics-, cultural, and weather-related events." The agency described the move as necessary to resolve conflicting federal appellate decisions and to put event contracts “squarely within the CFTC’s regulatory remit under the Commodity Exchange Act.”
The proposal runs to roughly 40 pages of explanatory text and defends the CFTC’s interpretation against recent court reasoning. In its filing the agency argues event contracts are “commonly known to the trade as swaps,” have characteristics similar to binary options, and can carry measurable financial or economic consequences — for example ticket sales, advertising revenue, player bonuses and local business income when a team advances in playoffs.
The proposed inclusion follows a split among federal appeals courts: the Third Circuit held in April that Kalshi’s sports contracts met the federal swap definition; the Ninth Circuit in August found similar contracts were likely not swaps; and the Sixth Circuit rejected swap status in September. The CFTC says these divergent rulings have produced “widespread confusion” about the reach of federal derivatives law and that a clear definitional amendment is warranted.
How the interim final rule draws a line between swaps and gambling
The interim final rule establishes a two-part test to exclude a traditional gambling product from the swap definition. To qualify for the exclusion a product must both:
Be offered by a provider authorised under state or tribal gambling laws and be regulated as gambling within that authorisation; and
Not be traded on an organised exchange or another marketplace where transactions are executed among multiple participants or are individually negotiated.
That framework separates conventional operator-run sportsbooks and casino games — where customers place wagers with an operator under house rules — from prediction‑market exchanges where participants trade contracts and prices form through buyer-seller interaction. The agency explicitly states that the exclusion is not dispositive for all products; offerings that fail these two requirements still must be evaluated individually against the statutory language of the Commodity Exchange Act.
"Casino-style gambling products are not derivatives," CFTC Chairman Michael Selig said in the agency's announcement, adding the Commission was codifying limits on its remit that mirror historic treatment of state-regulated products.
The interim final rule takes immediate administrative effect upon Federal Register publication; the Commission invoked an exception to normal rulemaking timing because of pending litigation and conflicting appellate rulings. A 30‑day public comment window will follow publication.
Legal context: courts, states and outstanding questions
The package arrives as litigation over federal jurisdiction intensifies. The CFTC cites an Oct. 7 Supreme Court filing by 39 states and the District of Columbia supporting New Jersey’s petition for review of the jurisdictional question. Despite the agency’s actions, courts retain the authority to interpret the Commodity Exchange Act; the Sixth Circuit has already held that Ohio and Tennessee gambling laws would not be preempted even if certain sports contracts qualified as swaps.
The CFTC’s proposed inclusion and the interim exclusion do not automatically settle the underlying legal disputes. The inclusion requires a final rule to be effective, and courts can reach interpretations of the CEA independent of the agency’s rulemaking. The Commission’s filings directly address the reasoning used in the Ninth Circuit decision, including that court’s reliance on CFTC Regulation 40.11, and press a statutory reading that places event contracts under federal derivatives jurisdiction.
Practical implications for exchanges, sportsbooks and states
For organised prediction‑market exchanges that trade event contracts, a final rule adopting the CFTC’s proposed language would ratify federal oversight of those instruments. For state‑licensed casinos and sportsbooks that meet the interim rule’s two criteria, the adopted exclusion preserves state and tribal regulatory authority and keeps those products outside the swap regulatory regime.
Operators and legal teams should note these implementation mechanics:
The proposed amendment needs a final rule before it becomes binding; that process will include a separate public-comment period.
The interim final exclusion is effective on Federal Register publication but remains subject to public comment and potential judicial review.
Products that superficially resemble either side of the divide may still require product-by-product legal assessment to determine whether they qualify as swaps.
The Commission linked the two actions as complementary: the proposal aims to assert federal jurisdiction over event contracts traded on exchanges, while the interim final rule aims to preserve traditional state and tribal authority over casino‑style gambling and operator‑run sportsbook wagers.
Why this matters now for market participants
Market participants face immediate regulatory uncertainty but also clearer signals about how the CFTC intends to draw boundaries. The split case law from the Third, Ninth and Sixth Circuits created pressure for agency action; the CFTC has responded with a proposal that would extend the swap definition and an exclusion that protects state‑regulated gambling products from being swept into federal derivatives oversight. The companion rules will be central to litigation and to industry compliance planning over the coming months.
"These products are commodity derivatives squarely within the CFTC’s regulatory remit under the Commodity Exchange Act and are within the agency’s exclusive jurisdiction," Chairman Michael Selig said in the announcement on 9 October 2026.
Regulatory teams at exchanges and state gaming authorities should monitor the Federal Register publication and prepare submissions for the forthcoming 30‑day comment windows. For background on how rule changes have affected operators in other sectors see our coverage of regulatory shifts in regulation and market responses in news.
Frequently Asked Questions
When do the CFTC’s new measures take effect?
The interim final rule excluding qualifying casino‑style gambling takes effect on publication in the Federal Register and will be followed by a 30‑day comment period. The proposed amendment to include event contracts in the swap definition must be issued as a final rule before it takes effect.
What test does the interim final rule use to distinguish gambling from swaps?
The rule requires two criteria: the product must be offered by a provider authorised and regulated under state or tribal gambling laws, and it must not be traded on an organised exchange or similar multi‑participant marketplace. Products failing those two requirements still require individual evaluation against the Commodity Exchange Act.
Which courts have issued conflicting rulings on whether sports contracts are swaps?
Three federal appeals courts have diverged: the Third Circuit found Kalshi’s sports contracts were swaps in April; the Ninth Circuit in August found they were likely not swaps; and the Sixth Circuit rejected swap status in September. The CFTC cited those conflicts as part of its justification for rulemaking.
Tags
About the author
Eleanor Whitfield
Regulatory Affairs Correspondent
Eleanor Whitfield tracks gambling legislation, licensing decisions, and regulator enforcement across key markets — from the UKGC, MGA, and Germany's GGL to Spain's DGOJ and the state-by-state map in the Americas. The reporting answers three questions precisely: what changed, where, and who it affects, with jurisdictions, effective dates, and penalty figures named exactly as published. Compliance officers and operators read Eleanor Whitfield to know which rulebook moved before their next board meeting.
More from Eleanor Whitfield