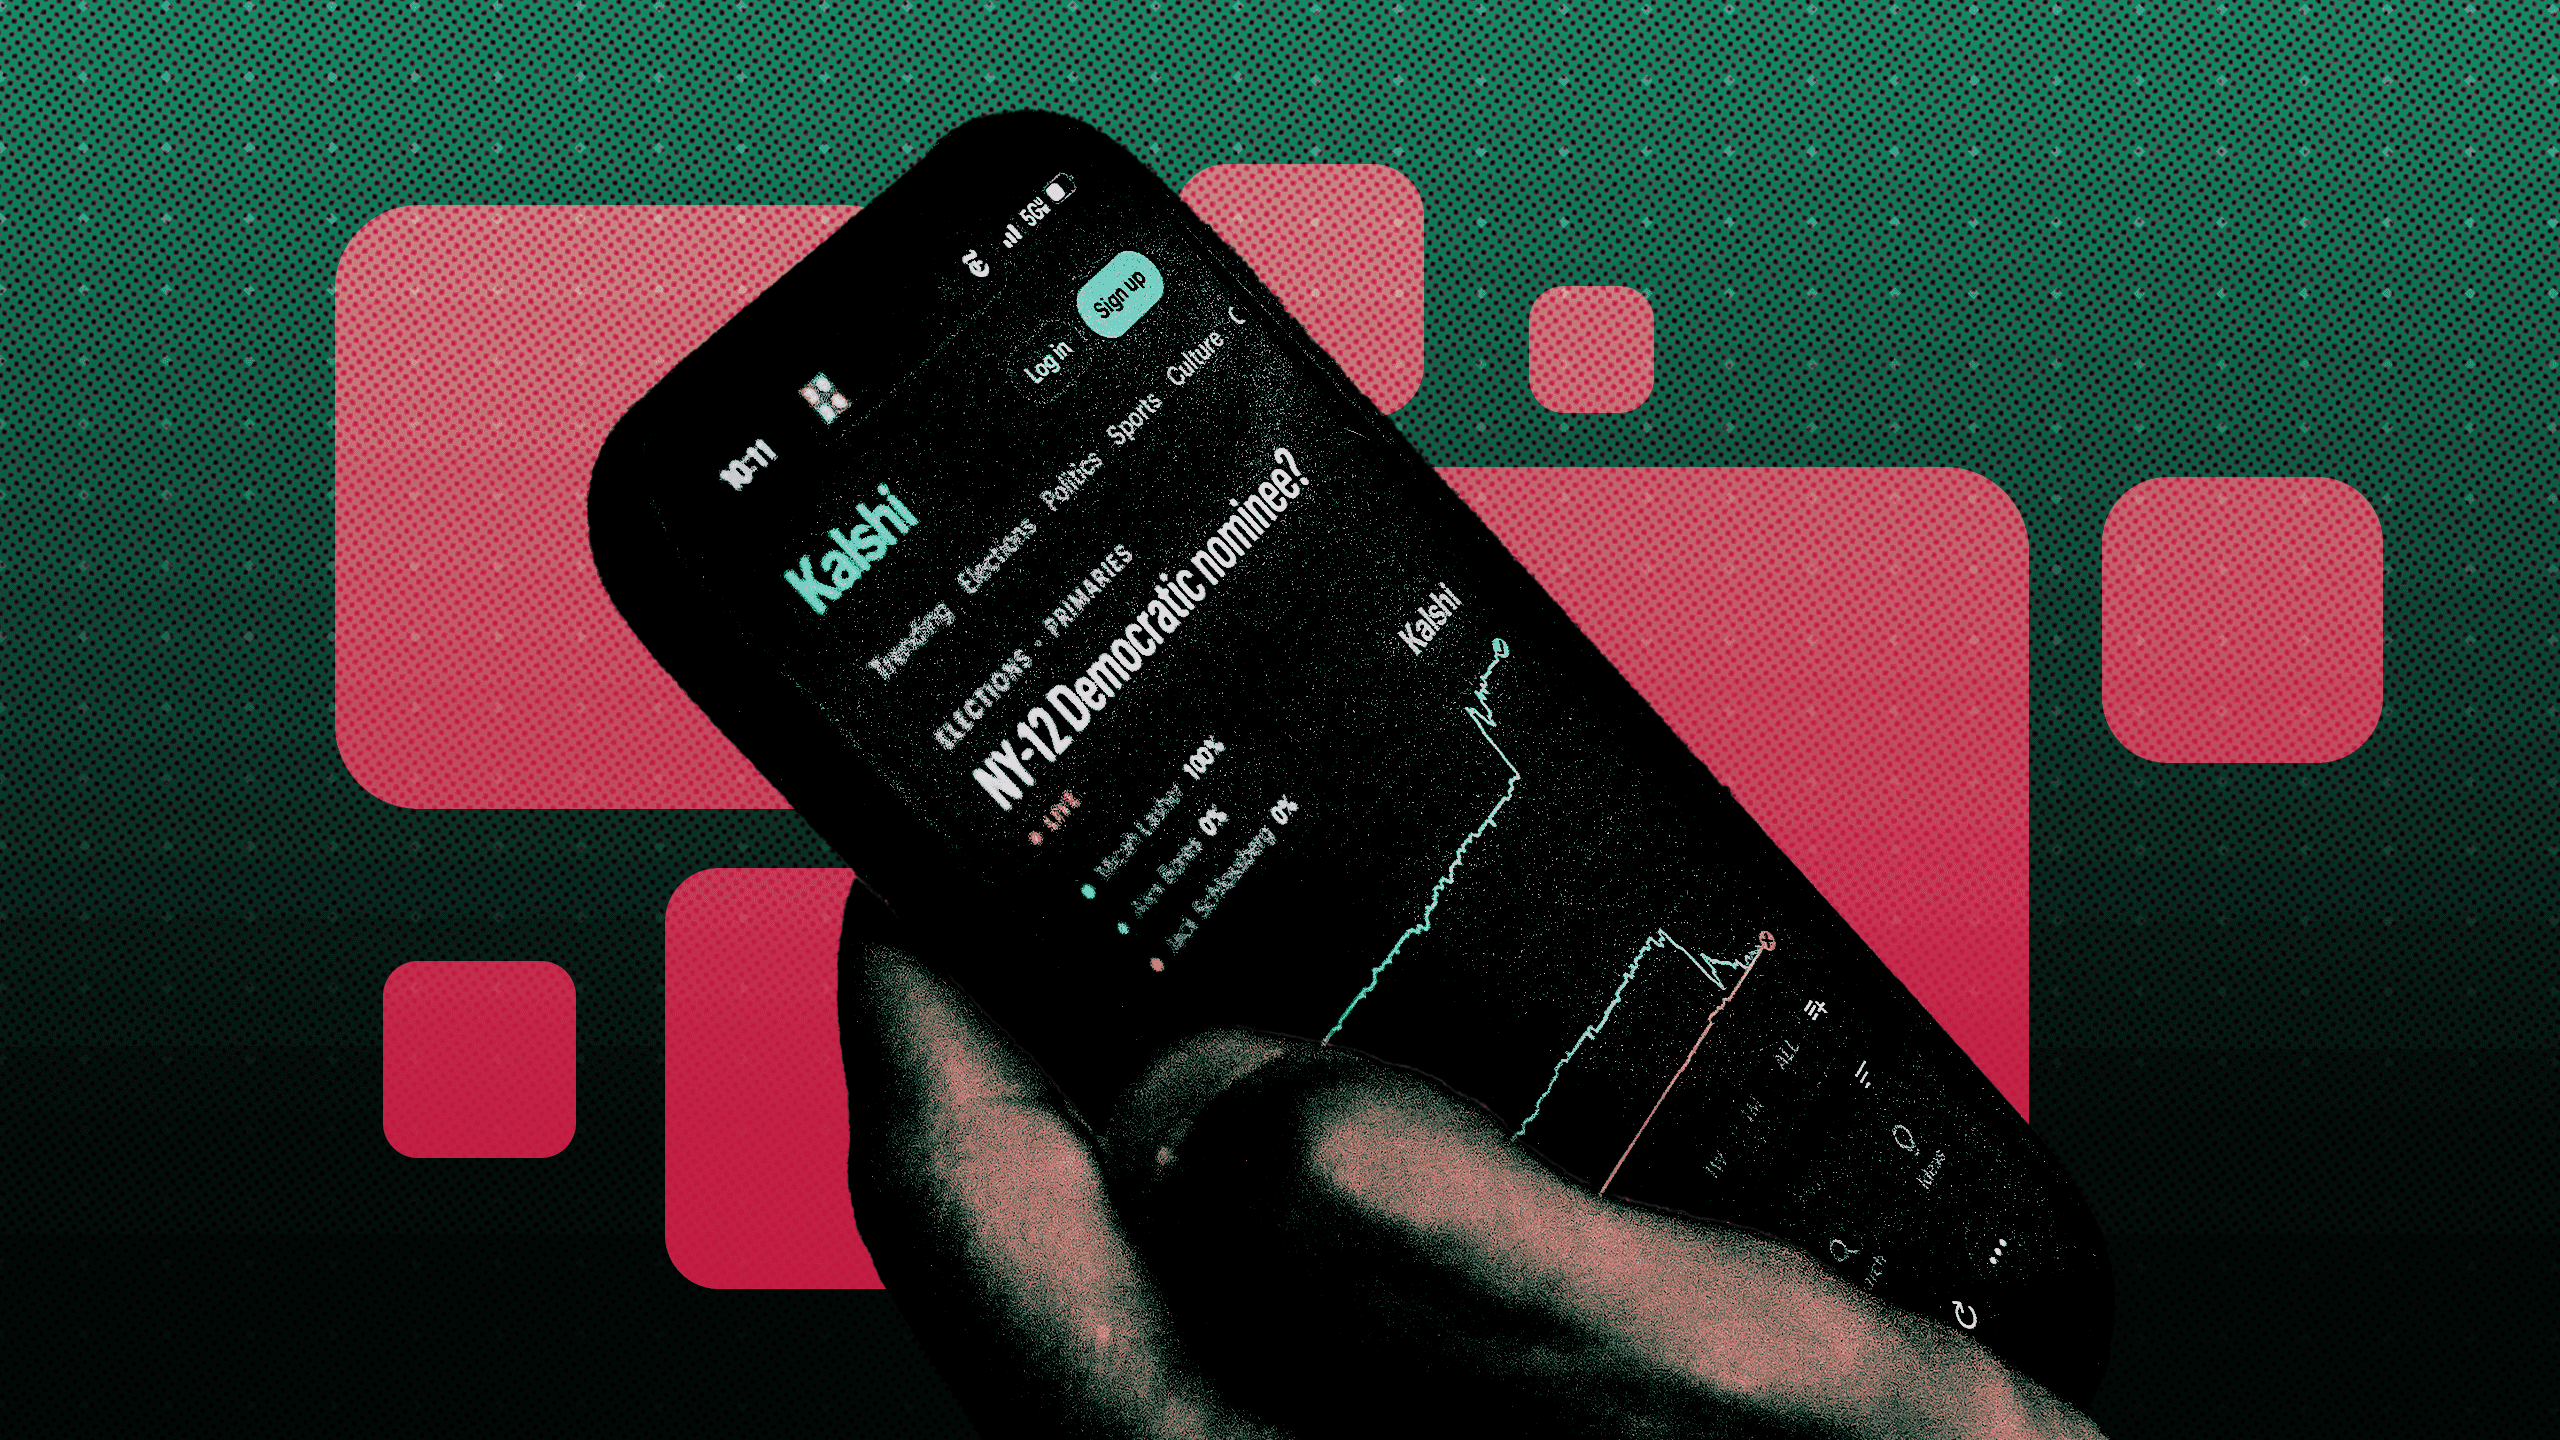
Kalshi offers 5% quarterly cap on affiliate trading amid CFTC proposal
Proposal would limit a parent-owned trading arm to 5% of volume and require public disclosure.
Key Takeaways
- Kalshi offered to limit its affiliate trading desk to 5% of betting volume each quarter in a CFTC comment letter.
- The company proposes quarterly public disclosure of affiliates’ trading volume by wager type and independent financial surveillance.
- A 5% maker-volume cap would have equalled about $2.3 billion in September, per Aldrin Research.
- Kalshi Trading accounted for roughly 1.5% of exchange volume year-to-date, according to the company.
Kalshi told the Commodity Futures Trading Commission on Monday it will accept a cap that limits its subsidiary trading desk to 5% of betting volume each quarter on its prediction market exchange. The submission is part of the CFTC’s public comment period on a proposed conflict-of-interest rule aimed at exchange-affiliate relationships where a firm owns both an exchange and a principal trading arm.
Kalshi’s offer and the mechanics of the 5% quarterly cap
Kalshi’s letter proposes that an affiliated trading arm may not exceed 5% of volume in any quarter, and that the cap would apply across both single-event bets and parlays executed through a request-for-quote system outside the central order book. The company frames the cap as an industry-wide, uniform ceiling rather than a bespoke restriction aimed only at Kalshi.
The firm argues the limit should encompass maker volume and RFQ activity alike, preventing affiliates from shifting activity between market structures to evade a rule. Kalshi also pressed for a bright-line definition of affiliate relationships “based on voting-interest and ownership percentage.”
What Kalshi asks the CFTC to require beyond the cap
Kalshi recommends several specific compliance measures be written into any final rule:
mandatory public disclosure of affiliates’ trading volume for each wager type on a quarterly basis;
independent financial surveillance of affiliated relationships involving principal trading arms;
compliance checks to ensure informational barriers, including separate physical offices for the exchange and the trading arm.
The firm said it already follows best practices for information barriers but wants the CFTC to codify requirements that would make expectations uniform across the market.
Where Kalshi parts company with the CFTC proposal
Kalshi opposes elements of the CFTC’s draft it describes as measures that would effectively neuter an affiliated trading arm’s ability to operate profitably. One prominent example in the proposal would force affiliated trading arms to accept last priority at every price in the order book, giving execution priority to independent oddsmakers.
Kalshi called that sort of rule “operationally burdensome while easily evaded through gamesmanship” and urged the agency to favour measurable limits like the 5% cap and external surveillance instead of structural execution disadvantages.
"We support affiliated market making only on a narrowly limited basis, under programs that are disclosed to the public and filed with the CFTC," Kalshi spokesperson Elisabeth Diana wrote in an email.
Why the CFTC is focused on exchange-affiliate relationships
The Commodity Futures Trading Commission opened the comment period to address perceived conflicts where an exchange operator also controls a principal trading desk that transacts on the same platform. The agency’s proposal lists potential "risks" arising from that corporate structure and seeks public input on remedies that would protect market integrity and retail customers.
The rule has attracted more than 50 public comments so far, with views ranging from calls for an outright ban on principal trading by exchange affiliates to arguments against restraints. The CME Group urged the CFTC to consider a ban on affiliate principal trading, while Fanatics argued against restricting affiliates’ market activity.
Kalshi’s letter is notable because the company explicitly acknowledged for the first time the risk the CFTC highlighted and proposed a measurable, industry-wide cap as an alternative to more prescriptive interventions.
Scale and context: how meaningful is 5% for Kalshi and the market
Kalshi tasked outside research to show the cap’s potential scale. Aldrin Research calculated that, if confined to maker volume, a 5% cap would have represented roughly $2.3 billion in September. Kalshi Trading, the company’s affiliate trading arm, has accounted for approximately 1.5% of volume on Kalshi’s exchange year-to-date, according to Elisabeth Diana.
Proponents of affiliated trading arms make a liquidity argument: affiliates can provide market making where independent liquidity providers are unwilling to step in. Critics counter that affiliates could be used to steer profits back to the parent company, a practice the CFTC appears intent on limiting.
Market and regulatory implications
If the CFTC accepts a 5% cap and disclosure requirements, exchanges would have to build reporting flows to publish affiliates’ volume by wager type each quarter. That change would increase transparency across the small but growing prediction-market sector and give regulators a clearer audit trail for any suspected abuses.
Kalshi’s recommended definition of affiliate status tied to voting-interest and ownership percentage would also narrow disputes about which entities fall under the rule. The company wants surveillance to be performed by independent parties, which would add cost but also standardise oversight across exchanges.
What vendors and exchanges should expect next
Technology vendors supplying surveillance, reporting and order-book controls can expect demand for tools that segment affiliate flow, produce wager-type breakdowns and log physical separation of trading desks. Operators will need to demonstrate compliance not only through policy documents but through auditable systems and quarterly public disclosures.
The CFTC will review submissions received during the comment period before publishing a final rule or revised proposal. Kalshi’s filing makes clear the company prefers a quantitative ceiling and third-party surveillance over structural execution penalties that could designate affiliates as perpetual price-takers.
Remaining questions for the CFTC and market participants
Key unresolved points include whether the 5% figure is appropriate across different-sized exchanges, how the cap should be enforced when affiliates trade indirectly, and what penalties would follow breaches. The CFTC will have to weigh competing views, including calls for a full ban by major industry participants, against proposals that aim to preserve some affiliate market-making while tightening transparency and oversight.
Kalshi’s submission puts a concrete alternative on the table, anchoring the debate around a single, measurable ceiling and a set of surveillance and disclosure requirements rather than execution priority rules.
Frequently Asked Questions
What did Kalshi propose to the CFTC regarding affiliate trading?
Kalshi proposed capping any affiliated trading arm at 5% of betting volume each quarter and asked for public quarterly disclosure of affiliates’ trading volume by wager type, plus independent financial surveillance and defined affiliate criteria based on voting-interest and ownership percentage.
How large would a 5% cap be in dollar terms?
A 5% cap confined to maker volume would have represented about $2.3 billion in September, according to Aldrin Research cited by Kalshi in its filing.
How much volume does Kalshi’s trading arm currently account for?
Kalshi said Kalshi Trading has accounted for approximately 1.5% of volume on its exchange year-to-date, per spokesperson Elisabeth Diana.
Which parts of the CFTC proposal does Kalshi oppose?
Kalshi opposed measures that would force affiliated trading arms to take last priority at every price in the order book, describing such execution disadvantages as operationally burdensome and easy to evade.
Tags
About the author
Oliver Grant
Industry Technology Correspondent
Oliver Grant covers the technology and business machinery of iGaming — platform and data deals, AI and compliance tooling, affiliate and marketing shifts, and the quarterly numbers behind them. The reports lead with the announcement, name the vendors and figures exactly as published, and separate genuine capability from press-release promise. When a supplier ships a new engine or a regulator tightens ad rules, Oliver Grant explains what actually changes for the companies involved.
More from Oliver Grant