SJM’s first half after satellites: revenue -21%, adjusted EBITDA +3%, market share 9.8%
Interim report shows smaller top line, wider margin and HK$30.2bn debt after satellite exits.
Key Takeaways
- SJM reported H1 2026 net revenue of HK$11,590 million, down 20.8% year-on-year.
- Adjusted EBITDA rose 3.3% to HK$1,701 million and the margin widened to 14.7%.
- SJM’s share of Macau GGR fell to 9.8% from 12.9% after losing nine satellite casinos.
- Group debt increased to HK$30,217 million at 30 June 2026 and gearing rose to 56.2%.
- Grand Lisboa Palace’s GGR rose 12.9% but its adjusted property EBITDA fell to HK$22 million.
SJM Holdings reported total net revenue of HK$11,590 million for the six months to 30 June 2026, a decline of 20.8% from HK$14,640 million a year earlier, while adjusted EBITDA rose 3.3% to HK$1,701 million, the group said in its interim report filed on 28 September 2026. The period is the company’s first half without the nine satellite casinos that left its books during 2025; management says the focus is now on optimising asset productivity amid a wider loss and higher debt.
SJM interim report 2026: revenue, EBITDA and the satellite effect
The headline revenue drop reflects the absence of the nine satellite casinos, which produced HK$5,647 million of gross gaming revenue (GGR) and just HK$153 million of adjusted property EBITDA in the first half of 2025. Group net gaming revenue fell 22.5% to HK$10,560 million, and gross gaming revenue declined 18.5% to HK$12,084 million (approximately $1.55 billion).
Commissions and incentives rose 27.8% to HK$1,524 million. Electronic gaming GGR was down 29.1% and non-rolling GGR, which covers mass-market play, fell 21.8%, while rolling GGR increased 32.9% to HK$1,461 million. The adjusted EBITDA margin widened to 14.7% from 11.2% a year earlier.
Macau market share and satellites: how SJM’s footprint changed
SJM’s share of Macau’s gross gaming revenue dropped to 9.8% from 12.9% a year earlier. Its share of mass-market table revenue fell to 12.3% from 16.1%, while VIP GGR share nudged up to 4.2% from 3.7%.
The regulatory backdrop was the 2022 revision of Macau’s gaming law, which required satellite casinos to operate only on premises owned by a concessionaire after the end of 2025. The interim report notes: "On 30 December 2025, Casino L'Arc Macau became one of the self-promoted casinos under SJM, while the other eight satellite casinos ceased operations during 2025." The disposals removed low-margin GGR from SJM’s top line.
More gaming revenue in SJM-run casinos; performance by property
Excluding the satellites, SJM says its own casinos generated HK$12,084 million of GGR in H1 2026, compared with HK$9,174 million a year earlier — a rise of roughly 32% by the report's figures. The gains were concentrated at the Peninsula properties.
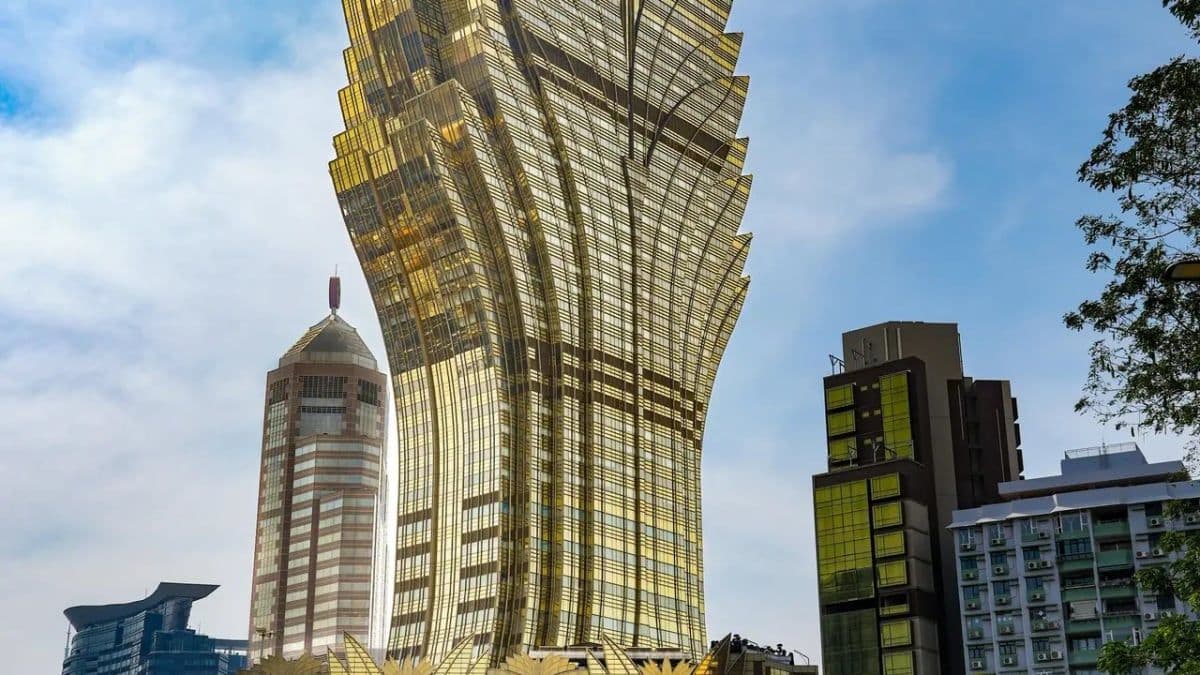
Grand Lisboa Palace in Cotai increased GGR 12.9% to HK$3,315 million, but its adjusted property EBITDA fell 73.2% to HK$22 million and hotel occupancy slipped to 92.9% from 98.1%.
Grand Lisboa’s GGR rose 7.1% to HK$3,838 million, with property EBITDA stable at HK$860 million.
Other properties, which include Casino Lisboa, Casino Oceanus at Jai Alai and Casino L'Arc (acquired December 2025), saw GGR rise 85.7% to HK$4,931 million and adjusted property EBITDA increase 44.2% to HK$939 million.
The report makes clear the satellites delivered revenue with very little margin; the nine satellites produced a property EBITDA margin under 3% in H1 2025. Redeploying tables from the satellites raised gaming revenue in SJM’s own venues, but not uniformly in profit contribution.
Balance sheet, debt profile and capital structure
SJM held HK$3,486 million of cash and HK$30,217 million of debt at 30 June 2026, compared with HK$3,335 million of cash and HK$27,257 million of debt a year earlier. Bank loans increased to HK$18,347 million from HK$16,222 million at end-2025.
In January 2026 a subsidiary issued US$540 million of 6.50% senior notes due 2031 to refinance syndicated bank loans; notes maturing in 2026 were no longer outstanding at 30 June. Of a syndicated revolving credit facility totalling HK$11.5 billion, HK$2.35 billion remained available at the period end. The gearing ratio rose to 56.2% from 54.4% at end-2025. The report states 63.7% of borrowings mature in one to two years and a further 15.6% mature within one year.
A convertible bond of HK$1,906 million held by the controlling shareholder, Sociedade de Jogos de Macau, S.A. (STDM), falls due on 22 June 2027.
Management priorities and operational responses
Management says the transition to a direct management model is complete and that priorities now are optimising asset productivity, strengthening the premium customer proposition and running a group-wide cost programme. The interim report highlights the opening of the second phase of the Crystal Palace gaming area at Hotel Lisboa on 10 August and the redeployment of tables into Grand Lisboa Palace.
"Following the successful completion of the transition to a direct management model, management's focus has shifted towards optimising asset productivity, strengthening the premium customer proposition and further enhancing the Group's overall competitiveness and operational resilience," the report says.
Headcount fell to about 19,400 at 30 June 2026 from about 20,300 a year earlier, a reduction of roughly 900 staff or 4%. SJM declared no interim dividend.
Where the numbers leave SJM and what to watch next
The group shows a better margin on a smaller base, while the balance sheet tightness remains the real constraint. Grand Lisboa Palace is the property to watch: higher GGR has yet to translate into meaningful property EBITDA, which was HK$22 million on nearly HK$3.94 billion of revenue in the period. The refinancing cushion provided by the 2031 notes carries a 6.50% coupon but most borrowings come due within two years, making the success of the productivity programme crucial ahead of the next funding round.
For market context on Macau and regulatory shifts affecting concessionaires, see recent coverage in the regulation and news sections.
Frequently Asked Questions
How much did SJM’s revenue change in the first half of 2026?
SJM’s total net revenue for H1 2026 fell by 20.8% to HK$11,590 million from HK$14,640 million in H1 2025, according to the interim report filed on 28 September 2026.
Why did SJM’s adjusted EBITDA improve despite lower revenue?
Adjusted EBITDA rose 3.3% to HK$1,701 million because the nine satellite casinos that left the group in 2025 contributed little profit; those satellites produced HK$5,647 million of GGR but only HK$153 million of adjusted property EBITDA in H1 2025, so removing them boosted group margins.
What is SJM’s current debt and near-term maturities profile?
SJM had HK$30,217 million of debt at 30 June 2026, with 63.7% of borrowings maturing in one to two years and a further 15.6% due within a year; a subsidiary issued US$540 million of 6.50% senior notes due 2031 in January 2026.
Which property remains the weakest performer for SJM?
Grand Lisboa Palace remains the weak link: GGR rose 12.9% to HK$3,315 million, but adjusted property EBITDA fell 73.2% to HK$22 million and hotel occupancy declined to 92.9% from 98.1%.
Tags
About the author
Oliver Grant
Industry Technology Correspondent
Oliver Grant covers the technology and business machinery of iGaming — platform and data deals, AI and compliance tooling, affiliate and marketing shifts, and the quarterly numbers behind them. The reports lead with the announcement, name the vendors and figures exactly as published, and separate genuine capability from press-release promise. When a supplier ships a new engine or a regulator tightens ad rules, Oliver Grant explains what actually changes for the companies involved.
More from Oliver Grant