Germany’s Betting Shop Market Contracts as Online Channels Capture 74% of Stakes
Regulated stakes hit €8.3bn in 2025 while retail locations decline to about 2,300.
Key Takeaways
- Regulated sports betting recorded approximately €8.3 billion in wagering stakes in 2025.
- The German Sports Betting Association reported about 2,300 dedicated betting shops in 2025, down from broader counts earlier in the decade.
- Digital channels generated roughly 74% of regulated sports betting stakes in 2025 and about 76% in H1 2026.
- The Glücksspielstaatsvertrag 2021 increased licensing and local approval requirements for physical betting shops.
Germany's betting shop market has contracted materially as online wagering takes the majority share of regulated stakes. Regulated sports betting recorded approximately €8.3 billion in wagering stakes in 2025, while the German Sports Betting Association reported roughly 2,300 dedicated betting shops that year. The national gambling regulator's data show digital channels generated about 74% of regulated sports betting stakes in 2025, rising to an estimated 76% in the first half of 2026.
Market scale and recent trajectory
The German regulated sports betting market delivered strong growth earlier in the decade but has since slowed. In 2015 tax-reported wagers were approximately €4.8 billion. By 2019 that had almost doubled to €9.3 billion, and the market reached about €9.4 billion in 2021. After the pandemic the expansion cooled: €7.9 billion in stakes in 2023, €8.2 billion in 2024 and €8.3 billion in 2025. The German Sports Betting Association's June 2026 market review recorded annual growth of 1.2%.
Physical distribution has reduced from the broader counts of the past. A 2016 report by Germany's state gambling authorities estimated between 4,000 and 5,000 private betting acceptance locations, including terminals in kiosks, bars and other premises. A 2023 pferdewetten.de investor presentation estimated around 2,700 dedicated retail betting shops, while the DSWV's figure for 2025 is approximately 2,300, suggesting a material contraction in dedicated retail outlets over recent years.
Where the bets are being placed
The national regulator GGL's official market monitor separates stakes by channel. Physical sports betting produced approximately €2.17 billion in stakes during 2025, compared with €6.09 billion placed online. That distribution made retail account for about 26% of regulated wagering stakes in 2025. Early 2026 figures indicate the online share has edged higher to about 76% of regulated stakes for the first six months.
For independent franchisees the shift to digital is commercially acute. Customers wagering on mobile devices do not pay shop rent or other fixed premises costs. That cost mismatch creates asymmetric risk for local operators carrying fixed overheads while distribution migrates to online platforms operated centrally by major brands.
Regulation and its commercial consequences
The Glücksspielstaatsvertrag 2021 changed licensing, player protection and supervision across Germany. Physical betting shops require permissions beyond an operator's authorisation under GGL guidance, and individual German states maintain additional rules including minimum-distance restrictions from schools and other gambling premises. The result is a higher compliance burden for new and existing locations and more uncertainty for franchisees who invest in premises before securing local approvals.
Regulatory disruption has also affected operators directly. In July 2024 the German gambling authority revoked the sports betting permission held by IBA Entertainment Limited, the former operator associated with Bet3000. The company challenged the decision and pursued legal remedies. By 2025 cooperation plans involving the Bet3000 group and pferdewetten.de had been revised, and the GGL's whitelist later identified I.B.C. Sportsbetting Limited as the licence holder for bet3000.de.
Economics for operators and franchisees
Aggregate market figures conceal margins and distributions. According to the DSWV, around €6.4 billion was paid back to customers as winnings in 2025, while operators paid roughly €420 million in sports betting taxes. Industry advertising expenditure was about €136 million and sponsorship spending €47 million. Those costs precede operator payroll, technology and premises expenses.
A 2024 pferdewetten.de investor presentation estimated networks of different scale: about 1,150 Tipico locations, 292 Tipwin shops and 252 Bet3000 outlets. Scale delivers advantages in brand recognition and reach, but it does not eliminate regulatory risk or guarantee profitability for individual franchisees working under fixed-cost constraints.
As new licenses become scarcer and approvals tighter, acquisition and conversion of existing licensed locations has become a strategic route for operators. Franchisees may receive approaches to change providers or migrate to alternative networks, creating opportunities for some and heightened commercial risk for others if the terms are unfavourable.
Looking ahead: consolidation and selective survival
Germany's retail network still supports employment and local businesses. The DSWV estimated that approximately 2,300 betting shops supported about 6,700 jobs in 2025. Survival in the next decade will favour operators running profitable locations rather than those seeking maximum network size. The market is likely to consolidate around fewer, stronger operators that can manage regulatory continuity, technology reliability and sustainable commercial terms for partners.
Prospective investors and franchisees should expect stricter scrutiny of trading results, clearer commission structures and explicit contingency plans covering licence losses, platform outages and franchise termination. Those are practical conditions illustrated by recent regulatory actions and the shifting distribution of wagering away from bricks-and-mortar outlets.
"A betting shop operator can invest money in a location, negotiate a lease and prepare the premises, only to discover that obtaining the necessary approval is considerably more complicated than originally expected," the market analysis noted.
"Physical betting shops require the relevant permissions in addition to the betting operator's authorisation," reads current GGL guidance.
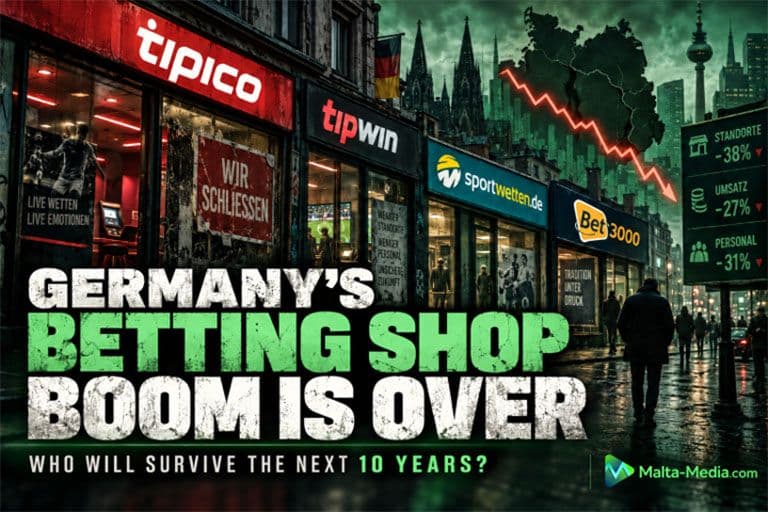
For established retail brands — Tipico, Tipwin, sportwetten.de and Bet3000 among them — the test will be whether they can sustain licensed market access while delivering terms that leave local partners able to cover their fixed costs. The era when opening another shop reliably captured local demand has passed. The question now is which operators and franchisees adapt successfully.
Frequently Asked Questions
How large was Germany's regulated sports betting market in 2025?
Germany's regulated sports betting market recorded approximately €8.3 billion in wagering stakes in 2025. The DSWV also reported that about €6.4 billion was returned to customers as winnings that year.
How many betting shops operated in Germany in 2025?
The German Sports Betting Association reported approximately 2,300 dedicated betting shops in 2025. A 2023 pferdewetten.de presentation had estimated about 2,700 dedicated retail locations.
What share of regulated betting was placed online in 2025?
Online channels generated around 74% of regulated sports betting stakes in 2025, with the online share rising to about 76% in the first half of 2026 according to the GGL market monitor.
What regulatory change most affects physical betting shops in Germany?
The Glücksspielstaatsvertrag 2021 introduced stricter licensing, player protection and supervision that require physical betting shops to obtain additional permissions beyond an operator's authorisation, and states impose location restrictions such as minimum distances.
What happened to Bet3000's licence in Germany?
In July 2024 the German gambling authority revoked the sports betting permission held by IBA Entertainment Limited, the former operator linked to Bet3000; the company disputed the decision and later the GGL whitelist identified I.B.C. Sportsbetting Limited as the licence holder for bet3000.de.
Tags
About the author
Marcus Webb
Industry Deals Correspondent
Marcus Webb covers the deal flow of the gambling industry — operator strategy, M&A, market entries, and product launches from sportsbook rebrands to full platform migrations. The reports name the companies, valuations, and jurisdictions exactly as disclosed and separate the announcement from its market impact. When a group consolidates a brand or a challenger launches into a new state, Marcus Webb explains who gains, who pays, and what closes next quarter.
More from Marcus Webb